Learning how to start a small business feels exciting at first. However, the excitement often fades when paperwork and choices pile up. Therefore, you need one clear sequence that you can follow calmly. Indeed, this guide gives you that sequence from idea to opening day.
Firstly, you will work through business idea validation before you spend heavily. Secondly, you will complete market research, planning, funding, and registration in order. Finally, you will finish with a practical small business launch checklist you can reuse. Consequently, nothing important gets skipped or done twice.
Admittedly, official guidance can feel fragmented across many linked pages. For example, the SBA 10 steps to start a business are helpful, yet they sit across separate resources. Similarly, many checklist blogs offer thin lists without costs or timing advice. Therefore, this article combines the full sequence, likely costs, and common delays in one place.
What Are the First Steps to Start a Business?
Understandably, most beginners ask where the journey actually begins. In fact, the first steps to start a business are validation, research, and a simple written plan. Moreover, those three steps protect every decision that follows them. Consequently, rushing past them usually creates expensive problems later.
Think of the steps to starting a business as a chain rather than a menu. For instance, your structure choice affects your taxes and your funding options. Likewise, your location choice affects your licences and your daily costs. Therefore, completing each link in order keeps the whole chain strong.
Below, you will find a complete business startup checklist in a sensible order. Additionally, each stage explains what to do, what it may cost, and what can delay you. Ultimately, you can move at your own pace without losing your place.
Step 1: Test Your Idea Before You Spend
Firstly, write your idea in one plain sentence that names the customer. For example, state who you serve, what problem you solve, and how you charge. Subsequently, test whether real people recognise that problem in their own lives. Indeed, honest reactions matter more than polite encouragement from friends.
Business idea validation does not require a finished product at all. Instead, you can interview potential customers and ask about their current habits. Additionally, you can create a simple waiting list page and watch genuine sign-ups. Therefore, weak interest becomes visible before you sign a lease.
How Can You Validate an Idea Cheaply?
Firstly, speak to people who already pay for similar solutions today. Secondly, ask what frustrates them and what they wish existed instead. Moreover, listen carefully for repeated complaints, because repetition signals real demand. Consequently, your offer can target a proven frustration directly.
Meanwhile, a small pre-sale or pilot can test willingness to pay. For instance, a limited trial for a few customers reveals pricing problems early. However, you should keep promises modest while you are still learning. Ultimately, a validated idea gives lenders and partners far more confidence.
Step 2: Do Market Research That Actually Helps
Firstly, market research for startups should answer three practical questions for you. For example, who buys, who competes, and what price does the market accept? Additionally, your research should reveal how customers currently find similar businesses. Therefore, vague industry reports alone will not guide your daily choices.
Start locally, even if you plan to sell online later. Indeed, nearby competitors show you real pricing, reviews, and service gaps. Similarly, customer reviews reveal complaints that your business can fix immediately. Consequently, reading reviews carefully often produces your best opening ideas.
Furthermore, talk to suppliers and complementary businesses in your area. For instance, they often know seasonal patterns and busy periods that newcomers miss. However, you should verify important claims through official or primary sources. Ultimately, good research reduces guessing without slowing you down unnecessarily.
Additionally, study how established operators move products and serve customers reliably. For example, this supply chain improvement playbook shows why visibility matters early. Indeed, delivery problems can damage a new reputation very quickly. Therefore, plan your supply basics before your first big order arrives.
Step 3: Write a Business Plan You Will Actually Use
Firstly, a business plan turns scattered ideas into decisions you can check. Moreover, lenders and landlords often ask to see a written plan. Consequently, writing one early saves you frantic rewriting under deadline pressure. Indeed, even a concise plan beats a perfect plan that never exists.
Include your offer, target customer, pricing logic, and expected costs inside it. Additionally, describe how you will attract customers during your first months. For instance, explain your channels, your opening offer, and your follow-up process. Therefore, marketing becomes a planned activity rather than a hopeful afterthought.
Subsequently, add simple financial forecasts based on cautious assumptions. However, you should label estimates clearly and avoid presenting guesses as facts. Similarly, note what would need to change if sales grow more slowly. Ultimately, a flexible plan helps you adjust without panicking.
Growth planning also belongs in this document from the beginning. For example, this guide to advanced digital marketing for business growth can shape your customer acquisition thinking. Likewise, thinking ahead prevents frantic hiring and messy systems later. Therefore, revisit your plan whenever a major assumption changes.
Step 4: Build Your Startup Costs Checklist
Firstly, list every cost category before you commit to any single purchase. Indeed, a startup costs checklist prevents the classic problem of forgotten expenses. Moreover, fees vary by state, city, industry, and business model. Therefore, treat any figures you see elsewhere as planning prompts, not promises.
Your list should separate one-time setup costs from recurring monthly costs. Additionally, it should include a contingency buffer for surprises and delays. For instance, equipment repairs and slow approvals commonly disrupt opening budgets. Consequently, a buffer protects your launch date and your stress levels.
| Cost Category | What It Usually Covers | Planning Note |
|---|---|---|
| Registration and licences | State filing, local permits, industry licences | Fees vary by state and industry |
| Premises and utilities | Deposit, rent, basic services, signage | Deposits often fall due before trading |
| Equipment and stock | Tools, technology, opening inventory | Compare leasing with buying outright |
| Professional help | Accounting, legal advice, insurance setup | Early advice can prevent costly errors |
| Marketing and website | Branding, site build, opening promotion | Reserve funds beyond launch week |
| Working capital | Wages, supplies, bills before revenue settles | Often the most underestimated category |
Subsequently, rank each item as essential, useful, or deferrable for opening. However, do not defer legal, safety, or tax requirements for cosmetic upgrades. Indeed, customers forgive plain décor far faster than unreliable service. Ultimately, disciplined spending keeps cash available for real problems.
Step 5: Decide How to Fund a Small Business
Firstly, understanding how to fund a small business starts with knowing your gap. For example, compare your total startup costs with your available personal savings. Additionally, decide how much risk you can carry without endangering essential household finances. Therefore, funding becomes a measured choice rather than a desperate scramble.
Options commonly include personal savings, bank loans, and microloans from community lenders. Moreover, some founders use grants, crowdfunding, or support from family under clear written terms. However, eligibility rules and repayment terms differ widely between these routes. Consequently, always check current terms directly with the provider or official source.
Indeed, the SBA website explains its loan programmes and connects founders with local assistance. Similarly, SCORE and Small Business Development Centers offer free mentoring in many areas. For instance, a mentor can review your plan before a lender ever sees it. Ultimately, preparation improves your credibility with every funding source.
Additionally, keep your personal and business finances visibly separate from the start. For example, clean records make applications, taxes, and partnerships far simpler later. Therefore, open dedicated accounts early, even if your initial trading is small. Consequently, you will thank yourself at your first tax deadline.
Step 6: Choose a Business Structure Carefully
Firstly, you must choose a business structure before you register formally. Indeed, common options include sole proprietorship, partnership, limited liability company, and corporation. Moreover, each structure affects liability, taxation, paperwork, and how owners are paid. Therefore, this decision deserves proper advice, not a rushed guess.
For example, simpler structures usually involve less formation paperwork and lower setup effort. However, they may offer less separation between personal and business obligations. Similarly, more formal structures can involve extra filings, meetings, and ongoing compliance duties. Consequently, the cheapest option today is not always the cheapest overall.
Admittedly, online explainers can help you compare the basic differences confidently. Nevertheless, your personal tax position and industry risks can change the right answer. Therefore, consult a qualified accountant or attorney before you file anything. Ultimately, an hour of advice here can prevent years of cleanup.
Sustainability also deserves a thought while you design your structure and operations. For instance, this overview of sustainable business architecture and the triple bottom line broadens how founders judge success. Indeed, profit, people, and environmental impact can be planned together. Consequently, early design choices become easier to defend and improve.
Step 7: Register Your Business and Get an EIN Number
Firstly, learning how to register a business starts with your state registration portal. Indeed, most formation filings, name searches, and trade name registrations happen at state level. Moreover, some cities and counties require an additional local business licence. Therefore, check both state and local requirements for your exact location.
Secondly, confirm that your chosen business name is available and not confusingly similar. Additionally, check domain names and social handles if online presence matters to you. For example, a mismatch between your legal name and trading name confuses customers. Consequently, a short naming check now prevents rebranding costs later.
Why Do You Need to Get an EIN Number?
Firstly, many businesses need to get an EIN number for tax administration purposes. Indeed, the Employer Identification Number is issued by the IRS for business identification. Moreover, banks often request an EIN when you open business accounts. Therefore, apply through the official IRS website and avoid fee-charging imitation sites.
Subsequently, keep your formation documents, EIN confirmation, and licences in one organised folder. Additionally, note renewal dates in a calendar so nothing lapses unnoticed. For instance, missed renewals can interrupt trading or trigger avoidable penalties. Ultimately, tidy records make every later application faster.
Meanwhile, remember that registration alone does not cover every legal duty. For example, sales tax permits, employer obligations, and industry rules may still apply. Therefore, review the SBA and your state portal guidance for your sector. Consequently, you reduce the risk of an unpleasant surprise inspection.
Step 8: Sort Licences, Insurance, and Your Bank Account
Firstly, list every licence and permit your industry and location actually require. Indeed, food, health, construction, childcare, and transport businesses face extra rules commonly. Moreover, operating without a required permit can stop your launch entirely. Therefore, apply early, because approval timelines are outside your control.
Secondly, open a business bank account as soon as your documents allow it. Additionally, choose accounting software or a bookkeeper before transactions start piling up. For example, weekly bookkeeping habits prevent a year-end mountain of receipts. Consequently, you will always know whether the business is truly profitable.
Insurance deserves the same early attention as banking and bookkeeping. For instance, this guide to farrier insurance for a specialist trade business shows how cover should match real risks. Indeed, general advice rarely fits skilled or physical trades perfectly. Therefore, discuss your actual activities with a licensed insurance professional.
Furthermore, think carefully about practical services you will depend on daily. For example, this article on mistakes to avoid when choosing an employee transportation solution highlights vendor risks clearly. Similarly, rushed vendor choices create recurring costs and staff frustration. Ultimately, compare providers on reliability and terms, not headline price alone.
Step 9: Set Up Your Location, Suppliers, and Systems
Firstly, decide whether you truly need premises or can start from home. Indeed, many founders exploring how to start your own business overestimate their space needs. Moreover, a home start can preserve cash while you prove demand properly. Therefore, add premises only when customer or operational needs justify them.
If premises matter, however, location decisions can support or strain your model. For example, some founders study options like owner-financed land in Texas when buying suits their long-term plan. Nevertheless, buying property is a major commitment that needs independent legal advice. Consequently, never let enthusiasm replace due diligence on contracts and zoning.
Subsequently, confirm suppliers, delivery times, payment terms, and backup options in writing. Additionally, test your payment systems, booking process, and customer contact channels before opening. For instance, a soft opening with limited customers exposes workflow problems safely. Therefore, fix systems quietly before your public launch invites a crowd.
Marketing systems also need setup before launch day arrives. For example, reviewing digital marketing ROI strategies for business success helps you track spending sensibly. Indeed, you should know which channel produced each early customer. Consequently, your limited budget flows toward what demonstrably works.
Step 10: Follow the SBA Sequence and Launch
Firstly, compare your progress against the SBA 10 steps to start a business framework. In general terms, that sequence covers research, planning, funding, location, structure, naming, registration, tax IDs, licences, and banking. Moreover, your work above already follows that same logical order closely. Therefore, use it as a final cross-check rather than a separate project.
Secondly, turn the framework into your own dated action list with owners. Additionally, mark which items depend on approvals from outside your business. For example, licence approvals and landlord decisions commonly cause the longest waits. Consequently, submit those applications as early as the process allows.
| Launch Area | Final Check Before Opening |
|---|---|
| Legal | Registration, licences, and permits confirmed current |
| Money | Bank account open, prices set, payment systems tested |
| Operations | Suppliers confirmed, opening stock counted, backup plan noted |
| Customers | Website live, contact details correct, opening offer ready |
| Team | Roles agreed, schedules shared, basic training completed |
Finally, pick a realistic opening date and work backwards from it. Indeed, a soft opening often beats a grand opening for brand-new teams. Moreover, early customer feedback lets you correct pricing and service problems quickly. Ultimately, launching imperfectly but legally beats waiting forever for perfection.
Growth after launch needs the same structured thinking as starting. For example, this executive guide to scaling business growth shows how expansion decisions compound. Similarly, disciplined measurement keeps growth from overwhelming your cash and team. Therefore, schedule a monthly review from your very first month.
What Common Delays Should You Expect?
Firstly, name availability and registration corrections can slow your formation unexpectedly. Indeed, a rejected filing usually means resubmission rather than total failure. Moreover, waiting calmly and correcting details carefully resolves most such problems. Therefore, build slack into any date you promise to others.
Secondly, licence inspections and premises approvals often move at their own pace. Additionally, funding decisions can take longer when documents are incomplete or inconsistent. For instance, mismatched names across forms trigger avoidable questions from reviewers. Consequently, consistency across every document quietly speeds up your launch.
Meanwhile, stock delays and equipment delivery problems can shift your opening week. However, a backup supplier and a flexible soft opening reduce that pressure greatly. Similarly, hiring can take longer than expected in competitive local markets. Ultimately, planning for delays is not pessimism, it is professionalism.
Your Printable Small Business Launch Checklist
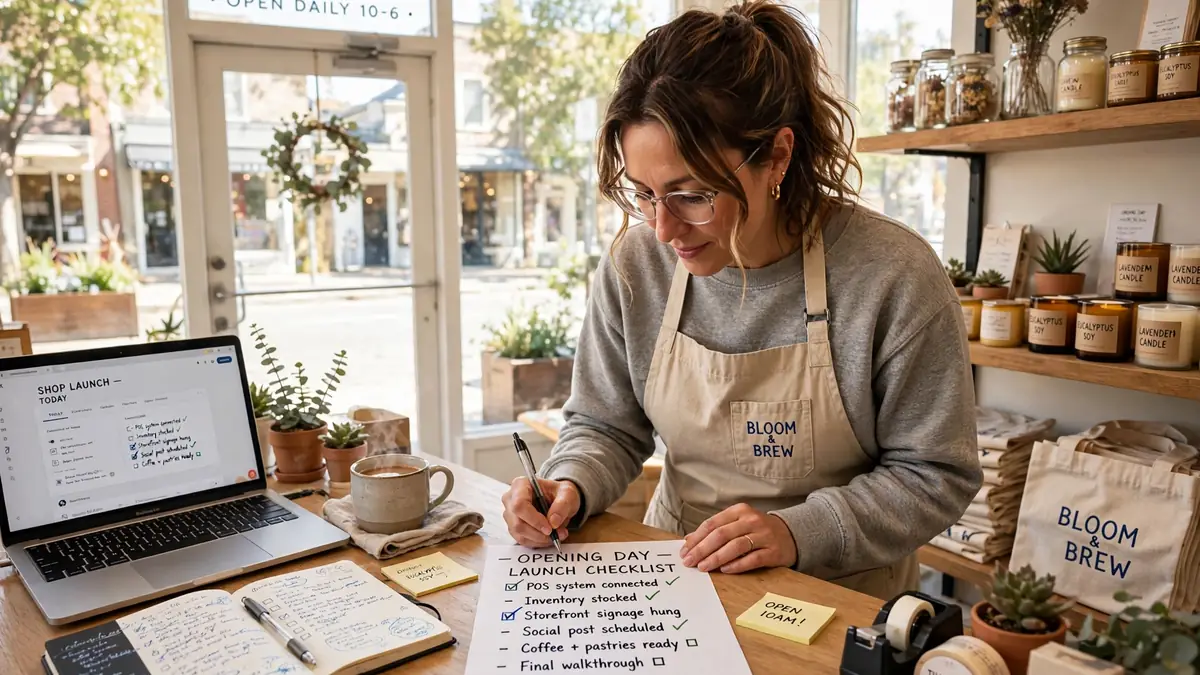
Firstly, copy this small business launch checklist into a document you can print. Secondly, tick each item only when you hold evidence that it is done. Moreover, add dates and document locations beside every completed line. Therefore, anyone helping you can see progress at a glance.
- Idea tested with real customers through business idea validation conversations.
- Market research for startups completed on customers, competitors, and pricing.
- Business plan written with costs, funding needs, and sales channels.
- Startup costs checklist prepared with one-time and monthly categories.
- Funding route chosen after reviewing how to fund a small business options.
- Decision made when I choose a business structure with professional advice.
- Registration completed after learning how to register a business locally.
- Application submitted to get an EIN number through the IRS.
- Licences, permits, insurance, and tax registrations confirmed.
- Decision made to open a business bank account and set up bookkeeping.
- Suppliers, systems, and payment methods tested before opening.
- Launch date set with a soft opening and feedback plan.
Indeed, anyone asking how to start your own business really needs this discipline. Additionally, the checklist works whether you open a shop, studio, or online service. For example, the order stays useful even when individual requirements differ by state. Ultimately, steady completion beats frantic multitasking every single time.
Frequently Asked Questions
How Long Does It Take to Start a Small Business?
Timelines vary widely depending on your industry, location, and funding route. However, simple home-based services usually move faster than licensed premises-based businesses. Moreover, approval waits often matter more than the tasks you control personally. Therefore, plan in ranges and keep your launch promises flexible.
Do You Need a Business Plan to Register?
Registration portals generally ask for formation details rather than a full plan. Nevertheless, lenders, landlords, and partners often request a plan separately. Indeed, writing one clarifies your costs before you commit to funding. Consequently, treat the plan as a management tool, not mere paperwork.
Where Should You Check Official Requirements?
Firstly, start with SBA.gov for federal guidance and programme explanations. Secondly, check your state registration portal and local government website for filings. Additionally, use the IRS website when you apply for an EIN. Ultimately, official sources should always override advice from forums or videos.
In conclusion, learning how to start a small business is mainly about correct order. Firstly, validate and research before you spend or sign anything significant. Secondly, plan your money, structure, registration, and systems with professional help where needed. Finally, launch, listen, and improve using real customer feedback every week.
Explore more practical guides on WordGlowUp.