Boating offers unmatched freedom on the open water. However, buying a brand-new marine motor requires substantial capital. Therefore, exploring Mercury Outboard Financing: Get Your Dream Boat Engine Now with Easy Financing helps boaters upgrade affordably. Modern boat owners want dependable four-stroke power and fuel efficiency. Yet, paying full retail cash upfront can strain household savings. Consequently, marine repower financing has become the most popular route for passionate boaters.
Historically, boaters had to buy complete boat packages to access marine loans. Today, specialized lenders offer standalone outboard financing for engine repower projects. As a result, you can keep your trusted boat hull while upgrading your propulsion. For readers seeking trusted guides on equipment financing, modern tools, and intentional living, visit the WordGlowUp homepage. Examining loan terms, credit requirements, and application procedures reveals why flexible financing makes repowering simple.
Why Boaters Choose Mercury Marine Outboard Engines
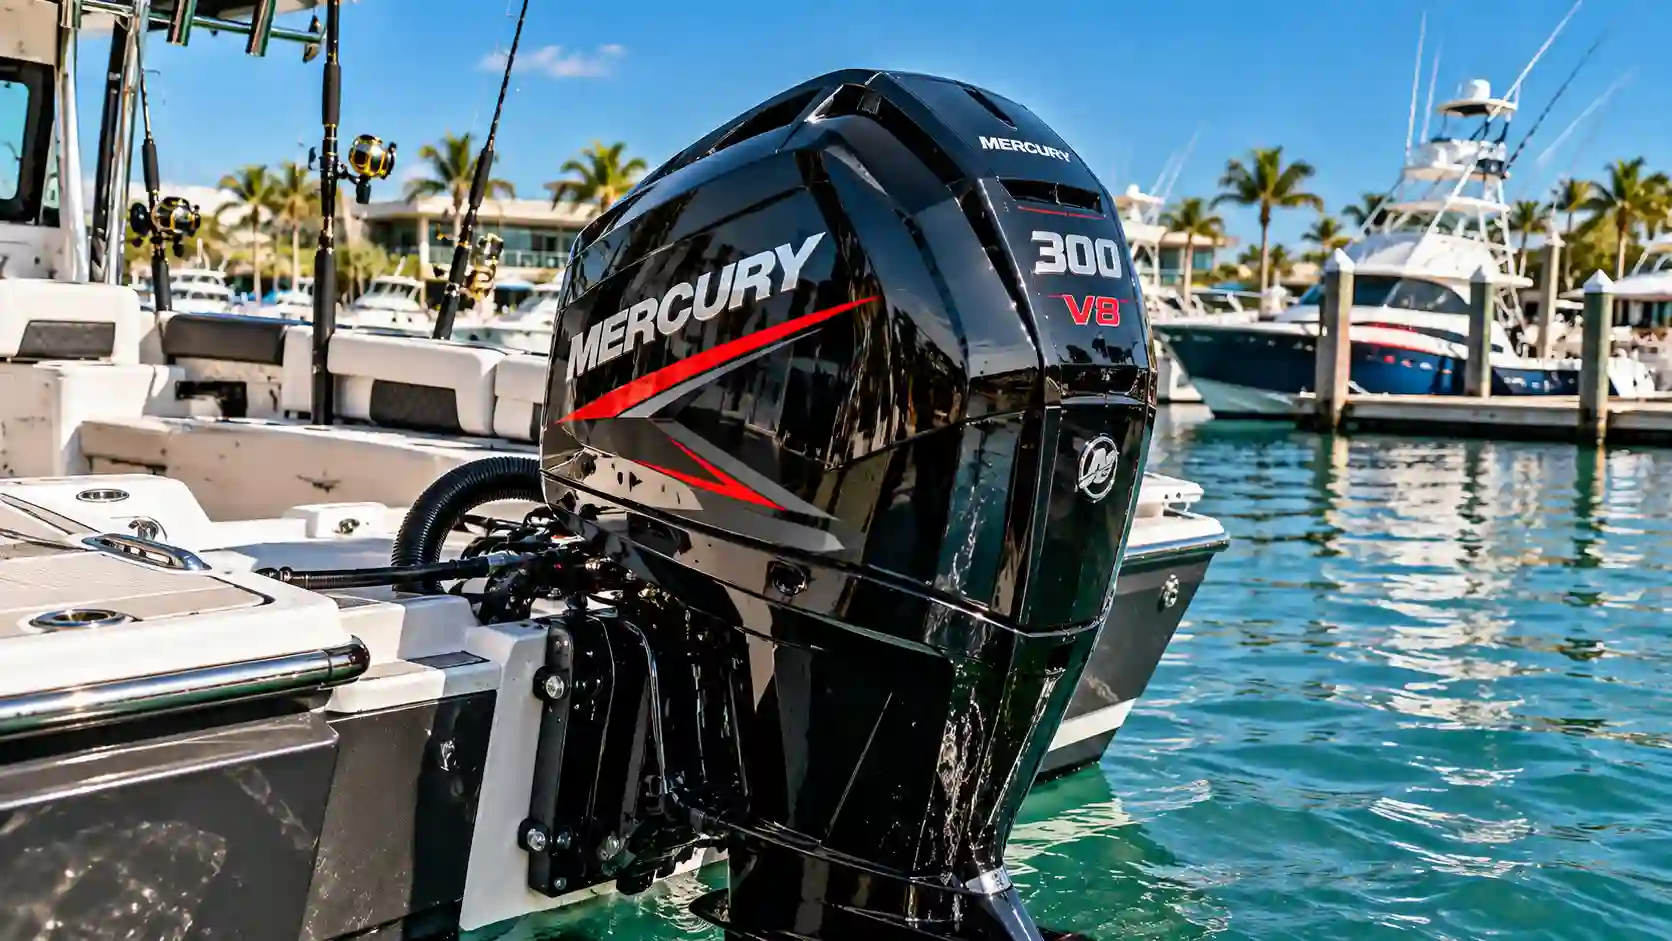
Mercury Marine leads the global marine industry in outboard innovation. Specifically, their four-stroke engines offer incredible torque, lightweight designs, and quiet operation. Boaters can choose from agile FourStroke models, muscular Pro XS fishing engines, or high-performance Verado motors.
Furthermore, modern Mercury outboards feature advanced digital throttle systems and controls. These smart systems optimize fuel consumption on every offshore trip. In addition, lower maintenance intervals save owners considerable money over time. Consequently, investing in a Mercury motor adds substantial resale value to your vessel.
Key benefits of choosing a Mercury outboard engine include:
- Superior Fuel Economy: Advanced fuel injection reduces fuel burn during long cruising runs.
- Whisper-Quiet Operation: Noise-dampening cowlings ensure peaceful conversation on open waters.
- Corrosion Protection: Advanced marine alloys and finishes protect engines against harsh saltwater conditions.
- Extensive Dealer Network: Certified service centers support warranty repairs and routine maintenance nationwide.
To explore more in-depth reviews on commercial equipment, digital platforms, and business systems, browse our curated Technology & Business category archive for practical technical guides.
How Mercury Outboard Financing and Repower Loans Work
Marine financing functions similarly to traditional vehicle loans. However, boat engines carry specialized depreciation and valuation guidelines. When you apply for outboard financing, the lender uses the engine as loan collateral.
In most cases, buyers secure fixed-rate installment loans. You repay the loan balance through equal monthly payments over two to seven years. Furthermore, buyers can roll rigging accessories, digital gauges, and professional dealer installation into a single loan. As a result, you face zero surprise out-of-pocket setup costs.
Comparing Marine Financing Channels
Review this side-by-side comparison to find the best financing option for your budget:
| Loan Option | Authorized Dealer Financing | Marine Specialty Lenders | Unsecured Personal Loans |
|---|---|---|---|
| Interest Rates (APR) | Promotional rates (often 4.99% – 8.99%). | Competitive fixed rates (7.49% – 10.99%). | Higher variable rates (9.99% – 18.99%). |
| Repayment Terms | 36 to 84 months. | 48 to 120 months on larger motors. | 24 to 60 months. |
| Collateral Requirements | The outboard engine secures the loan. | The boat and engine secure the loan. | Zero collateral required. |
| Application Speed | Same-day approval at the dealership. | 24 to 48 business hours online. | Instant to 24-hour digital approval. |
| Factory Promotions | Access to Mercury rebates and warranty perks. | Rarely includes manufacturer rebates. | Zero factory promotional perks. |
This comparison confirms that authorized dealer financing offers the lowest rates and best factory warranty promotions.
Credit Score Requirements and Down Payment Guidelines
Marine lenders evaluate several financial factors before approving an outboard loan. Understanding these criteria helps you prepare your application beforehand.
First, lenders examine your personal credit score. Most marine finance companies prefer a credit score of 660 or higher for competitive interest rates. However, specialized lenders offer subprime marine programs for scores between 600 and 640.
Second, down payment amounts vary based on loan size. Many promotional programs offer zero-down financing for qualified buyers. Nevertheless, putting down 10% to 15% lowers your monthly payments significantly. In addition, a solid down payment protects you from negative equity as the engine ages.
Protecting Your Marine Investment: Insurance and Warranties
Repowering your vessel requires proper insurance coverage and comprehensive warranties. Standard homeowner insurance policies rarely cover powerful standalone outboard motors.
Therefore, boaters must secure dedicated marine insurance with adequate hull and machinery limits. When negotiating marine policies or commercial equipment coverage, boat owners frequently review formal insurance protocols. For example, understanding statutory broker authorizations—such as the principles detailed in bor meaning in insurance understanding its impact on your coverage—ensures that insurance binders and warranty riders remain legally protected.
Furthermore, modern manufacturers operate under ethical production and operational principles. Aligning equipment investments with a sustainable business architecture triple bottom line ensures that marine manufacturers reduce emissions and protect marine ecosystems. Modern Mercury engines exceed strict EPA environmental standards, preserving waterways for future generations.
Embracing Marine Leisure and Intentional Living
Spending weekends on the water offers therapeutic mental benefits. Gliding across calm lakes or navigating coastal bays relieves weekly workplace stress.
This active outdoor lifestyle aligns perfectly with the restorative living principles celebrated in american lifestyle magazine your ultimate guide to modern living. Clean air, quiet mornings, and family fishing trips create a healthy domestic balance.
Moreover, reliable marine power allows families to explore coastal waterways without mechanical worries. Installing a dependable engine allows boaters to relax, enjoy water sports, and unlock unforgettable moments with lifestyle xperiences 365 live fully across sunny summer weekends.
Actionable 5-Step Guide to Securing Mercury Outboard Financing
Follow this simple step-by-step roadmap to finance your Mercury outboard engine:
- Determine Your Vessel’s Horsepower Limit: Check the capacity plate on your boat transom to avoid overpowering the hull.
- Request a Written Repower Quote: Ask an authorized dealer to include the motor, digital gauges, controls, and installation labor.
- Review Your Credit Profile: Check your credit report for errors to qualify for the lowest promotional APR rates.
- Compare Factory Financing Promotions: Look for Mercury retail promotions that include extended warranty years or reduced interest rates.
- Submit Your Application and Schedule Rigging: Finalize loan documents digitally and coordinate your repower installation date with the service shop.
Frequently Asked Questions About Mercury Outboard Financing
Can you finance just the outboard motor without buying a boat?
Yes. Many marine lenders and authorized Mercury dealers offer standalone repower financing specifically for boat owners upgrading their current engines.
What credit score do you need to finance a Mercury outboard?
Most lenders prefer a credit score of 660 or higher for prime interest rates. However, specialized lenders approve buyers with credit scores down to 600.
How long are loan terms for marine outboard engines?
Repower loan terms typically range from 36 to 84 months, depending on the engine’s total cost and your down payment.
Can rigging, labor, and new gauges be included in the loan?
Yes. Authorized dealers can roll rigging kits, propellers, steering lines, digital gauges, and installation labor directly into your financing package.
To learn more about our equipment financing research, consumer guides, and editorial team, explore our About Us page. If you have questions regarding marine loans, engine repowering, or general editorial feedback, please connect with our team through our Contact Us page.